
Checkbook - Account Tracker
- Rating
- 3.6
- Downloads
- 100.00K
- Content Rating
- Everyone
Checkbook - Account Tracker - Screenshots
Pros
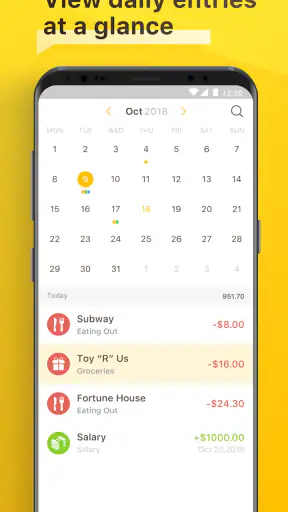
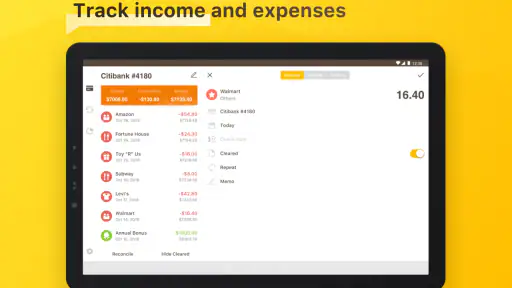
- Simple interface makes income and expense tracking quick.
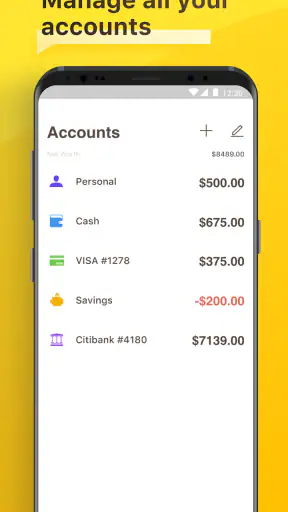
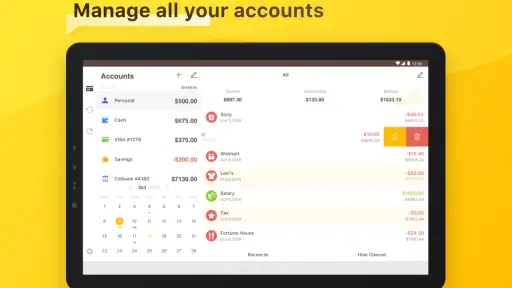
- Supports multiple accounts for better financial organization.
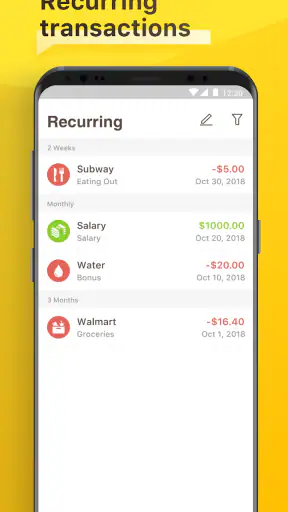
- Recurring transactions reduce repetitive manual entries.
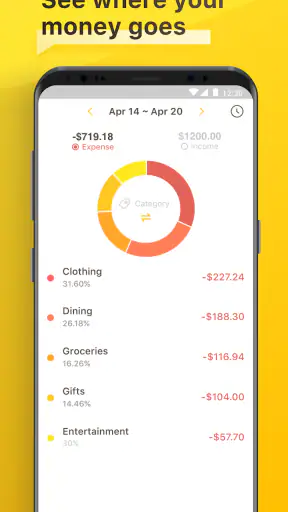
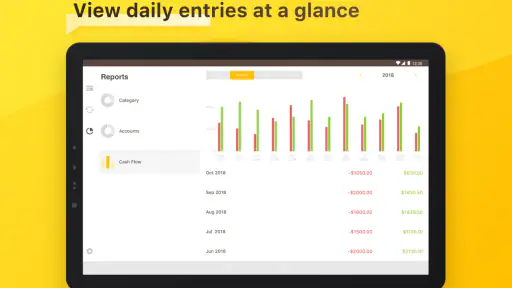
- Useful charts provide a clear view of spending patterns.
- Budget tools help monitor limits and financial goals.
Cons
- Some advanced features may require a paid upgrade.
- Manual transaction entry can become time-consuming.
- Limited bank synchronization may not suit every user.
- Reports may feel basic for detailed financial analysis.
- Backup and transfer options may depend on the platform.
Checkbook - Account Tracker - Description
- App Name
- Checkbook - Account Tracker
- Package Name
- com.appxy.checkbook2
- Developer
- TinyWork Apps
- Category
- Finance
- Last Updated
- Jul 24, 2015
- Version
- 2.1.2
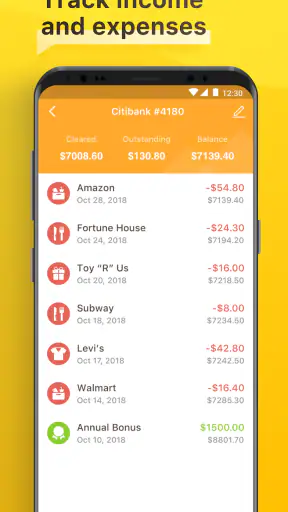
I started using Checkbook - Account Tracker because I wanted something simpler than a full banking app for recording everyday spending. Its basic idea is easy to understand: it gives me a digital register where I can enter money coming in and going out, then keep an eye on the running balance. That makes it especially useful for someone who still likes the clarity of a paper checkbook but wants the convenience of carrying the record on a phone.
This is a finance app from TinyWork Apps, and it is free to install. The current version is 2.1.2, it works on Android 7.0 and later, and it is rated for Everyone. The app has passed 100 thousand installs, with an average rating of 3.6 from roughly 9 thousand ratings and more than 4 thousand written reviews. Those figures suggest a useful but not universally loved tool, which matches my experience: it does its central job well, but it is not trying to replace a modern bank dashboard or a complete budgeting suite.
How it works in a shared household
The most practical way I found to use it was as a shared household record rather than as a replacement for online banking. For example, imagine two people using one checking account for groceries, fuel, school expenses, and recurring bills. One person pays for groceries with the physical card while the other later records the transaction in the app. The register can then show the balance after that purchase, even before the bank’s own transaction feed has settled.
That workflow is helpful because it separates two jobs that banking apps often mix together. The bank shows what has reached the account; a checkbook register lets me record what I have already committed to spend. If I buy something today but the charge remains pending, entering it immediately gives me a more realistic view of what is available. I still treat the bank as the authority, but the app becomes a practical day-to-day ledger.
There is an important household boundary here: this is not a shared workspace with automatic coordination. I would not assume that two people entering items on separate phones will see the same register or that changes will be synchronized between devices. For shared use, I would choose one primary device and agree that everyone records purchases there, or have one person maintain the register from receipts and messages.
That limitation sounds small until several people are involved. If one partner records a purchase on a personal phone and another records the same purchase later on the household device, the balance becomes misleading. The app is therefore best for a household with a clear recording routine, not for a group expecting live collaboration. A simple rule such as “the person who pays sends a receipt photo, and one person enters it each evening” makes the setup much safer.
Setting up accounts without mixing everything together
I recommend starting with one account and using it for a short trial period before entering every financial detail in the household. The point is not to build a perfect historical archive. It is to learn how the register behaves when transactions are entered, corrected, and checked against the real account. Once that routine feels comfortable, I would add other accounts only if they have a clear purpose.
Keeping account boundaries matters. A shared checking account, a personal account, and cash in a wallet should not be treated as one pool simply because the same person manages them. Even when the app allows several records, I would keep the labels unmistakable and avoid recording transfers as ordinary spending. Otherwise, the same money can appear to leave one account and disappear again as an expense, making the overall picture harder to understand.
My preferred routine is to record a transaction as soon as possible, then review the register against the bank once or twice a week. I would also leave a small note for anything unusual, such as a temporary authorization, a returned purchase, or a bill that has been entered but has not cleared. These details are more valuable than filling the app with old transactions that I can no longer verify.
A useful but easily overlooked habit is to correct mistakes immediately rather than adding a second entry to compensate for the first. If I type the wrong amount, editing the original transaction preserves a cleaner history than creating an unexplained adjustment. When the balance looks wrong later, a clean register makes it much easier to find the problem.
Coordination when more than one person pays
For couples or housemates, the app works best when it supports a simple agreement about responsibility. I would decide who owns the register, who sends spending details, and when the balance is checked. That may sound like household administration, but it prevents the most common failure: everyone assumes someone else entered the transaction.
One workable method is a daily handoff. Each person keeps receipts or sends a short message with the amount and purpose, while the register owner enters everything at a fixed time. Another method is to keep the device in a shared location and record purchases immediately. The first option is better when people are rarely together; the second is quicker when the household shares a tablet or one main phone.
I would not use this app as the only source for deciding whether a payment has actually cleared. The register is a planning tool, and its accuracy depends on the people entering information. A bank statement remains necessary for reconciliation. That distinction is particularly important for automatic bills, card payments made offline, and purchases that change after a tip or adjustment.
The lack of automatic bank-feed behavior is a weakness compared with many newer budgeting apps. Those services can reduce manual entry and categorize transactions for you, although they may also bring account-linking steps, privacy concerns, or clutter that a simple register avoids. Checkbook - Account Tracker wins when I want direct control and minimal dependence on a financial connection. It loses when I want transactions imported without effort.
Age, trust, and appropriate access
Because the app is rated for Everyone, it can suit a broad range of users, but that does not mean every user should manage a household account without guidance. A teenager learning to track allowance or small purchases may benefit from the register’s straightforward structure. An older relative who prefers a paper ledger may also find the digital format approachable if someone helps with the initial setup.
I would introduce it to a younger user as a record-keeping exercise, not as permission to make financial decisions independently. The app can show what has been entered, but it cannot replace a conversation about spending limits, private information, or who is responsible for checking the real balance. On a shared device, I would also make sure the person using it understands that the register may reveal sensitive amounts and transaction descriptions.
Trust is just as important between adults. If two people share one register, both need to agree that entries are visible and that corrections are discussed rather than silently made. The app does not create a family governance system for you. It gives you a ledger, so the household still has to decide who can view it, who can edit it, and how disagreements are resolved.
That makes the app a better fit for cooperative households than for situations where each person needs a private financial space. If I wanted separate personal budgets, automatic categorization, goals, or detailed reporting for each family member, I would look at a dedicated budgeting service instead. Here, the strength is the shared concept of a checkbook register, not a large set of household management tools.
Where the simple register is genuinely useful
The app’s biggest strength is that it encourages me to think in terms of a running balance. That is different from opening a bank app, seeing a number, and assuming it represents every commitment I have made. For people who regularly forget pending purchases or who still reconcile accounts manually, this approach can prevent avoidable overdraft surprises.
It is also useful for a small personal account that does not need a complex budget. A student tracking rent, transport, and food could use it without building a dozen categories. Someone managing a side account for household repairs could record deposits and payments in one focused place. A person who writes occasional checks may appreciate the familiar register model more than a chart-heavy finance app.
One practical tip is to use consistent descriptions. “Store” is too vague when several purchases happen there in one week, while “weekly groceries” or “cleaning supplies” makes later review more meaningful. I also prefer entering the actual transaction date rather than the date I remember it. That small discipline makes reconciliation easier and exposes gaps in the record.
Another useful approach is to treat recurring expenses as reminders for yourself, not as proof that the payment has completed. If I enter a regular bill early, I would mark it mentally as planned and verify it later against the bank. This prevents a common mistake in manual registers: assuming that an expected payment is settled simply because it appears in the list.
For cash spending, the app can be valuable only if I record purchases consistently. Cash is easy to forget, especially when several small transactions happen in one day. I would either enter each purchase immediately or keep receipts in one place until the evening. Without that routine, the register may look precise while quietly missing the very spending I most need to monitor.
Friction compared with modern finance alternatives
Compared with a paper checkbook, this app is easier to carry, easier to correct, and less likely to be lost in a drawer. Compared with a bank app, it offers a more deliberate record of spending but requires manual effort. Compared with a full budgeting app, it is narrower and probably less intimidating, but it will not give the same broad planning experience.
The choice depends on what I want to avoid. If I dislike connecting financial accounts to third-party services, manual entry is a reasonable trade-off. If I dislike typing every transaction, the trade-off becomes frustrating quickly. Someone with several cards, investments, loans, and shared accounts may outgrow this register because the work of maintaining it increases with every financial source.
The average rating of 3.6 reflects that middle position. The app is neither a polished all-in-one financial command center nor a disposable novelty. It can be dependable for people who want a focused ledger, but its usefulness is tied to personal discipline. I would not recommend installing it and expecting the app itself to organize a household’s finances automatically.
There is also a cost consideration. The download is free, while in-app purchases range from $0.99 to $19.99 per item. I would check what an optional purchase unlocks before paying and decide whether the extra capability solves a real problem in my routine. For a basic register, the free starting point is enough to judge whether manual tracking suits me, so I would not spend immediately.
Who should use it and who should skip it
I would recommend it to someone who wants a digital checkbook register, prefers entering transactions personally, and needs a lightweight way to track one or a few clearly separated accounts. It is particularly suitable for a household that can agree on one recording device and one reconciliation routine. It can also help a beginner understand how purchases affect an available balance.
I would be more cautious about recommending it to a person who expects automatic bank synchronization, shared editing across multiple phones, sophisticated categories, investment tracking, or detailed financial reports. Those needs point toward a broader budgeting product. I would also skip it if I know I will not enter transactions regularly; no register can compensate for missing information.
Privacy-minded users may appreciate not having to build their entire financial life around an automated connection, but they should still treat the phone and any shared device as sensitive. A household should avoid leaving the register open where visitors or children can casually inspect account details. The app’s Everyone rating describes its general content suitability, not a guarantee that every financial record is appropriate for every person to view.
My household verdict
After using it as a manual ledger, I see Checkbook - Account Tracker as a focused tool with a clear purpose. It gives me the familiar discipline of a paper checkbook while removing some of the inconvenience of carrying and correcting one. Its real value appears when I use it before spending decisions, not merely after the bank statement arrives.
For shared households, I would use one designated register, keep account boundaries clear, and agree on who enters purchases. I would reconcile it with the bank regularly and never confuse a manually entered item with a confirmed cleared payment. Those habits are not optional extras; they are what make the app trustworthy in everyday use.
My recommendation is simple: choose it if you want a controlled, manual account tracker, and choose a fuller budgeting app if you want automation or collaboration. TinyWork Apps has kept the concept understandable, and that simplicity is its main advantage. It is free to try, suitable for Everyone, and supported on older Android devices, but its modest rating also hints at the central trade-off: the app stays simple because it leaves much of the financial work to me.
For a person replacing a paper register, tracking a small account, or coordinating household spending from one shared device, that can be exactly right. For a family expecting separate logins, automatic updates, and built-in financial oversight, it is the wrong tool. I would recommend starting small, testing the recording routine for a week, and keeping it only if the running balance genuinely helps the household make better decisions.
FAQ
What is Checkbook - Account Tracker used for?
Checkbook - Account Tracker is designed to help you record and monitor personal finances in a simple checkbook-style interface. You can enter income, expenses, deposits, withdrawals, transfers, and other transactions, then review your balance and account activity. It is useful for people who want a clearer picture of daily spending without relying entirely on a bank’s mobile application.
Can I use Checkbook - Account Tracker for multiple accounts?
The app is intended for tracking more than one financial account, such as checking accounts, savings accounts, cash, credit cards, or other personal funds, depending on the features available in your version. Keeping accounts separate makes it easier to understand where your money is held and how it moves. Before downloading, check the current store listing for any account limits or premium restrictions.
Does Checkbook - Account Tracker connect directly to my bank?
Checkbook - Account Tracker primarily works as a manual transaction-recording tool rather than a replacement for online banking. In practice, you generally enter transactions yourself and compare the recorded balance with your bank statement. This can be beneficial for privacy and control, but it also means that the accuracy of your records depends on entering purchases, deposits, fees, and transfers consistently.
Is my financial information safe when using the app?
Because a checkbook tracker can contain sensitive information about your spending and account balances, you should review the app’s privacy policy and permission requests before using it. Avoid entering unnecessary banking credentials or confidential account details unless the official listing clearly explains why they are required. Also consider enabling any available passcode, biometric lock, backup, or device-security options.
Is Checkbook - Account Tracker free to download and use?
The availability of free features, advertising, subscriptions, or one-time purchases may vary according to the Android or iOS version and the developer’s current pricing. Basic transaction tracking may be available without payment, while advanced tools such as additional accounts, reports, synchronization, or backups could require an upgrade. Always verify the latest store description and in-app purchase information before downloading.


